Thursday, 19 November 2026

Money won't matter on a dead planet

Note: this is NOT investment advice - if in doubt, speak to a financial adviser. The ETFs referred to in this article are not the only products available - they were found using a mix of website and Google searches, including the FT.COM, and MSCI website. The author is not aware of any simple way to filter ETFs by the suggested criteria of sustainability preference and themes, apart from web and platform searches. If in doubt, seek professional financial advice.

I agree with George Monbiot that investing in renewables is great for the UK's energy security. But your financial adviser is unlikely to ask you about renewables. The most you can hope for are three or four questions: your attitude to risk; your preference for active or passive funds; your ESG/sustainability preference; and your preference for specific themes. Neither are you likely to be asked what future you hope for, beyond growth versus value... nothing imaginative like which Arup scenario you want to invest in, or your interest in specific themes such as the circular economy, electrification, or ecosystem restoration projects.

There is also a fifth question that is not always asked: what level of fees and decision-making are you comfortable with? Having spent a big chunk of my career developing passive ETFs, where the whole ethos is to low fees and investor choice, this strikes me as a fairly central question. Of course, we know that passive investment led to all sorts of distortions, not least the bloated flotation of Thus PLC at the height of the DotCom bubble, a story that is just as relevant today with the boom in US AI stocks.

So with this caveat - that passive ETFs are feeding the US AI bubble - is it even possible to build a low-cost sustainable fund? Or are we entering a new era of wealth managers and financial advisers?

Let's take the first and last questions together - should we all be active investors now? 

Let's start with the FCA evidence that higher fees lead to worse performance, and that passive investment leads to over-weighting of some stocks/sectors and a weakening of stewardship, governance and capital allocation. We'll use that as a guide to ignore active funds, and instead build a low-cost ETF base by choosing a sustainability overlay (benchmarks with stronger stewardship and governance). We'll then use bonds to adjust to our risk preference. Lastly, to be active allocators of capital, we'll keep money aside to make specific allocations in themes that align with our values.

Q1: sustainability preference. Depending how we feel about stewardship and governance, we add a stronger benchmark overlay (such as the exclusion of fossil fuel firms, and strong positive selection) or a weaker benchmark overlay (such as ESG tilts towards improved firms).

Zero ESG base: if we really don't care at all, we just buy the MSCI All World Index.

Low ESG base - conveniently split into US and ex-US, we can use the iShares ESG Aware MSCI EAFE ETF and iShares ESG Aware MSCI USA ETF as our ESG base, boosting ESG scores while staying close to the original index

Medium ESG base - if we want a medium overlay, the iShares MSCI World Screened UCITS ETF will reduce carbon intensity by around 30%, while excluding sectors such as tobacco and thermal coal

High ESG base - for the strongest overlay, basing our portfolio on the Xtrackers MSCI World ESG UCITS ETF will mean investing in a faster transition, reducing carbon intensity by around 50%, plus stricter ethical screens and ESG exclusions

Q2: attitude to risk. Next, we'll include bonds, depending on our risk preference. 

Low risk - don't even think of investing before you have reduced your debts, especially high interest debts such as credit cards

Medium risk - the traditional 60/40 equity/bond portfolio is not entirely dead. Sure, take on as much equity risk as your appetite allows, but include bonds to reduce overall risk. This is an opportunity for active capital allocation, too, by investing in community energy bonds available via an Ethex IFISA, or in tax-free NS&I green savings bonds. Alternatively, invest in UK Gilts to ensure you have cash when you need it - 0-5 year, for short-term cash; or all maturities, for long-term cash. If you like risk, include some corporate or overseas bonds. If you want to keep things simple and liquid, include some Premium Bonds.

High risk - if you really think this time is different, don't bother with any bonds, but max out your property loans and credit cards to invest in the ETFs under Q1. Don't come crying to me if things go badly wrong.

Q3: your preference for specific themes. I'm assuming by now that you've decided on your ESG base - one of the versions of the MSCI All World ESG indices listed above - and you've decided what percentage to put into bonds. There are various ways to bring in additional themes, take your pick:

Country/region themes - it's much easier to add than to subtract, by buying a suitable country ETF. Alternatively, rather than the MSCI All World, look for exclusions such as the iShares ESG Aware MSCI EAFE ETF above, which would reduce your exposure to the US.

Other themes. There are plenty of thematic and impact ETFs out there. The challenge here is to avoid buying into a bubble, and to avoid transaction fees. I set myself a rule to re-balance annually, to keep my transaction costs down. That also forces me to be more like Warren Buffett2, and invest in things where I have a connection or interest... so what does that mean for you? Themed ETFs and community bonds don't just cover sustainable energy but also sustainable food, the circular economy, electrification, commodities, green infrastructure, nature restoration, charities, farms, social enterprises... just remember caveat emptor!


Monday, 7 April 2025

Trump is right - the international economic model is broken


As we watch Trump blow up the international economic model, we should at least agree with him that the model needs to change. For too long, we have relied on the US as ‘consumer of last resort’, a model that was created in the 1970s and entrenched by Thatcherism and Reaganomics. Sure, the model imploded in 2007-8, and bank bailouts and the ensuing austerity made things worse, but it had already been broken by the export-led Asian miracle economies of the 1980s:


The Post-Keynesian accounting approach ‘shared by Godley, Baker, Hudson, Keen and others was predictively successful for the 2007-8 crisis, and also the theoretically most developed’ (Bezemer 2010).  But since 2008, China has diversified both its export markets and its investments, mimicking the long-running 'exorbitant privilege' of capital exports by the US, and we need to look beyond stock-flow consistent models.

To fully grasp this Trump moment, I suggest we look back to the interwar period. Then, Keynes proposed a system of multilateral clearing for trade imbalances. Creditor and debtors would be charged for racking up large surpluses and deficits, but with smaller tariffs (5-10%) on creditors. Adjustment would come by allowing debtors to competitively devalue and re-build their industrial base, accompanied by a ban on capital exports. In part, China's economic miracle was built by limiting US capital exports - but without the headwinds of US tariffs and a devaluation of the US Dollar.

There is a deal to be done, therefore, and one that will save the world from a different threat - climate inaction. We should accept Trump's assertion that the US Dollar needs to devalue, and that tariffs may be necessary to encourage surplus countries to make reciprocal investments in the US. But that should be conditional on the US accepting restrictions on their capital exports - US firms should not be investing in Taiwan, or in new oil projects outside of its borders. We could go further, and seize this opportunity to ban all new investments in fossil fuel extraction. It may not be possible to stop Trump investing in shale gas domestically, but a ban will mean that countries investing more rapidly in the energy transition will benefit first. 

There are other lesson from Keynes, too. Trump's tariff rates are way too high, and the lesson from Europe in the 1930s is that retaliatory tariffs make things worse - contributing to inflation and nationalism. Cooler heads are needed, as well as a cooler planet. Yes, the international economic model is broken; and yes, too, there is a deal to be done.

Friday, 13 March 2020

Laissez-faire economics won't save us from COVID-2050


A laissez-faire approach to coronavirus, no matter how much we get nudged - individual responsibility to wash our hands, avoid planes and public transport, and self-isolate - will not stop the spread of the virus. What the economy needs is not words, but a strong, fiscal response to supply the physical assets that we need to push this virus back. In those terms, the recent UK budget was not ambitious enough. 


I'm not talking about the supply of toilet rolls, sanitiser and pasta, I'm talking about spending on measures to restrict the spread of the virus. I don't know much about NHS Labs, but it appears they hit a supply side constraint because, despite scaling up and there being a 10-minute test available, the UK will "stop testing members of the public who display mild symptoms". The same is true of hospital beds, where UK hospitals rank amongst the lowest in Europe; on top of an NHS staff shortage and the closure of community hospitals. I know the evidence is mixed, but providing temperature checks at stations, ports, and airports could catch just over half of coronavirus-infected passengers. 


Specific supply side constraints are not solved by lowering general interest rates, but by strong and targetted fiscal policy. Yes, there has been some money for the NHS, but it has been constrained by ten years of austerity. From this weakened base, the cautious UK response could include more incentives for people to do the right thing and stay at home if they are sick, including the self-employed and low-waged. Given the low NHS base, the UK needs more stringent controls on the movement of people than our European and Asian neighbours, not less.


Where to start? As a climate activist, I would have no qualms about grounding flights for a few weeks.  Why not push harder on that net zero by 2050 door at the same time? After all, as my 13-yr old son joked last night, we don't yet know how bad the COVID-2050 strain will be. 


Indeed, our service industries depend upon the UK being a safe place to visit. Imagine if there was no yellow fever vaccine - with a fatality rate of about 5% - few people 'at risk' would travel to areas where yellow fever is endemic. Whether the case fatality rate for COVID-19 is similar or turns out to be less because of undiagnosed cases, there are around 1 billion 'at risk' over 60s today, forecast to double by 2050. Prepare for the worst, and hope for the best.


What does more stringent controls on movement mean? Ensure people can work from home for the same pay; cancel large gatherings and move to virtual events; use video calling in at risk settings, GP surgeries and care homes; offer online exams and tutorials at Universities; encourage less (and longer) overseas and other trips; help elderly neighbours get their groceries. These are familiar themes to climate activists - live locally and act globally.

Achieving net zero creates both supply and demand side problems, but the UK government should have few qualms about letting CO2-intensive companies fail under 'tooth and claw' capitalism if they are not going to meet those 2050 climate goals - this is not a time to spend £27bn on motorways and roads. Given the laisser-faire response of the UK and other governments it may be too late to hold back COVID-19. But it is not too late to plan for COVID-2050.

Thursday, 7 December 2017

Using Bloomberg From R and Excel


Bloomberg from R

First, you need to be logged on to Bloomberg.

If the Bloomberg/Excel add-in does not work, then:
1. Close Excel and/or R
2. Keep Bloomberg running
3. Go to Start-> Bloomberg -> API Environment Diagnostics
4. Click Start when the Bloomberg API Diagnostics window has loaded
5. If a “Login to wintrv…” message below then pops up, this occurs when Bloomberg isn’t open – it is highly recommended that you have Bloomberg running; you can proceed without it, but you may not be able to resolve some errors if you do so
6. Once the check is finished, you will get a 'Diagnostics completed' message
7. If the Repair button is available to press on the Bloomberg API Diagnostics window, it means it needs to run the repair and you should do so by clicking Repair (it should take a couple of minutes)
8. Once the check is done, and repair if necessary, the ideal state is all green ticks except for 2 yellow “!” for Dotnet Installation and Excel Throttle Interval only. Else, you can still run Excel or R-Studio and see if the Bloomberg-associated functionality is working.

# install the Bloomberg package, and connect
install.packages("Rblpapi")
library (Rblpapi)
blpConnect()

# get the Bloomberg data history for SPY US Equity - last 100 days - and plot it
x <-  bdh("SPY US Equity", "PX_LAST", start.date=Sys.Date()-100)
plot(x)

# find out what other fields are available for prices
res <- fieldSearch("price")
res

# get the Bloomberg data history for SPY US Equity - last 100 days - and plot it
x <-  bdh("SPY US Equity", "OPEN", start.date=Sys.Date()-100)
plot(x)

Bloomberg from Excel

As above, if the Bloomberg/Excel add-in does not work, then repair (Steps 1-8).
Open an Excel Sheet, and type the following into a cell:
Historical prices: BDH("F US Equity", "PX_LAST", “16/11/2000”, “15/11/2016”)
This will give you the last traded price (PX_LAST) for 'F US Equity (Ford Motor  Company) from 16/11/2000 to 15/11/2016. The first parameter must be the Bloomberg stock code.

For DMU students, this URL shows how to get data from Bloomberg into Excel.
Also for DMU students, this URL shows how to use Bloomberg.


Monday, 25 September 2017

Ukraine's path to prosperity


You can get an Uber in Ukraine. Investment is more difficult, because borrowing in local currency (Hryvnia) is expensive. The official interest rate is 12.5%, local currency mortgages cost around 20% and credit cards cost around 40%. To borrow more cheaply, many households took out USD mortgages prior to the Global Financial Crisis but, when the Hryvnia collapsed, these became unmanageable. Subsequently, the parliament (Rada) banned foreign currency mortgages and imposed a moratorium on the confiscation of property by the banks. The government finds it equally difficult to borrow cheaply, with the most recent sovereign Eurobond issue at 7.375%. The cheapest borrowing is reserved for privatised companies that export commodities: for example, LSE listed Ferrexpo, which is 51% owned by Rada member Kostyantyn Zhevago and exports iron ore pellets, has bond yields as low as 3.7%.  

Unsurprisingly, Ukranian public opinion is that the financial system is loaded against them. Two-thirds of sovereign bonds are issued in foreign currency, which means that Ukraine must have a constant stream of foreign currency to meet its payment schedules. When Ukraine does well, the Hryvina strengthens and foreign currency is easy to get. When Ukraine does badly, as it did after the conflict in the East, the Hryvina devalues and there is a scrabble for foreign exchange to satisfy creditors. Official statistics suggest that the central bank has enough foreign exchange reserves for about 3.5 months of exports, at $18 billion, but there is another $90 billion held privately by individuals. 


The conditionality attached to foreign loans is depressingly familiar, with the IMF requiring a maximum 3% public deficit, and the World Bank calling for sustainable public pensions. This, at a time when the minimum pension is little more than $2 per day.

And therein lies the trap. Public borrowing is heavily constrained, and private borrowing is too expensive. Notionally, the primary target of the central bank is inflation, and they have implemented tough measures to stabilise the foreign exchange rate. But lowering the interest rate requires reforms to reduce the cost of borrowing from local banks: better regulation, banking competition, less corruption, enforceable contracts, recognised accounting standards and clear accountability. Without deeper reforms, the risk is that the Rada will continue to make the same mistakes: hasty privatisations and sales of public land to ease the budget pressures but, in the process, creating the conditions for a new class of wealthy elites. Part of the problem is the Rada itself, which is unicameral (one legislative chamber) with code-based law. Here, the outlook for reform is less clear.

What’s to be done? At the Ukrfinforum last week (21/9/2017), Yanis Varoufakis called for a new Bretton Woods agreement. The World Bank and IMF could acknowledge that the financial system is heavily loaded against ordinary people, accept the need for International reforms, and back off on the conditionality around sequencing: they could support any measures that reduce the cost of borrowing, including an end to the war. The economy will turn round when Ukranians are confident and able to borrow and invest locally, which in turn will reduce Ukraine’s dependency on foreign exchange being earned by a small number of commodity exporters.

Wednesday, 25 January 2017

Infrastructure activism


The highlight of the inaugral NEKS conference was to hear Sir Vince Cable talking about Theresa May's industrial strategy, which he describe as a 'rebranding [of the 2011 strategy] with some good new features'. He reminded us that the UK abandoned interventionist policies in 1979, a state that remained until Mandelson's car scrappage scheme in April 2009, followed by support for the UK aerospace sector.

Sir Vince told us that he concocted a letter with Michael Heseltine, who had an adjacent office, asking David Cameron to be more strategic about UK government procurement. Two big ideas followed. The first was to encourage long-term, strategic thinking by government, leading to such things as the recently launched National Infrastructure Commission; the second was to directly support key sectors such as aerospace, cars, textiles, apprenticeships and University Innovation Centres. Sir Vince reminded us that we should also question economic wisdoms: in terms of revealed comparative advantage, the UK is supposed to put all its eggs in one basket and concentrate on financial services. BREXIT poses a new question for industrial strategy: do we 'take back control' and become more interventionist, or do we relinquish control to the markets?

In explaining how the UK handles infrastructure today, Bridget Roswell told us about the National Infrastructure Commission (NIC), an Executive Agency that reports to HM Treasury. The NIC is designed to circumvent short-term electoral cycles by developing long-term infrastructure plans for transport, energy, water, sewerage and telecoms. At the conference, I heard several different approaches to long-term planning, but the problems were the same: how do you measure success, which criteria do you use? Francesca Medda (UCL) described a portfolio structuring approach, designed to optimise a portfolio of projects combining negative NPV/high social value projects with positive NPV/lower social value projects. Others, such as Tim Foxon (SPRU), outlined ways to involve the local community in the appraisal and selection of suitable projects.

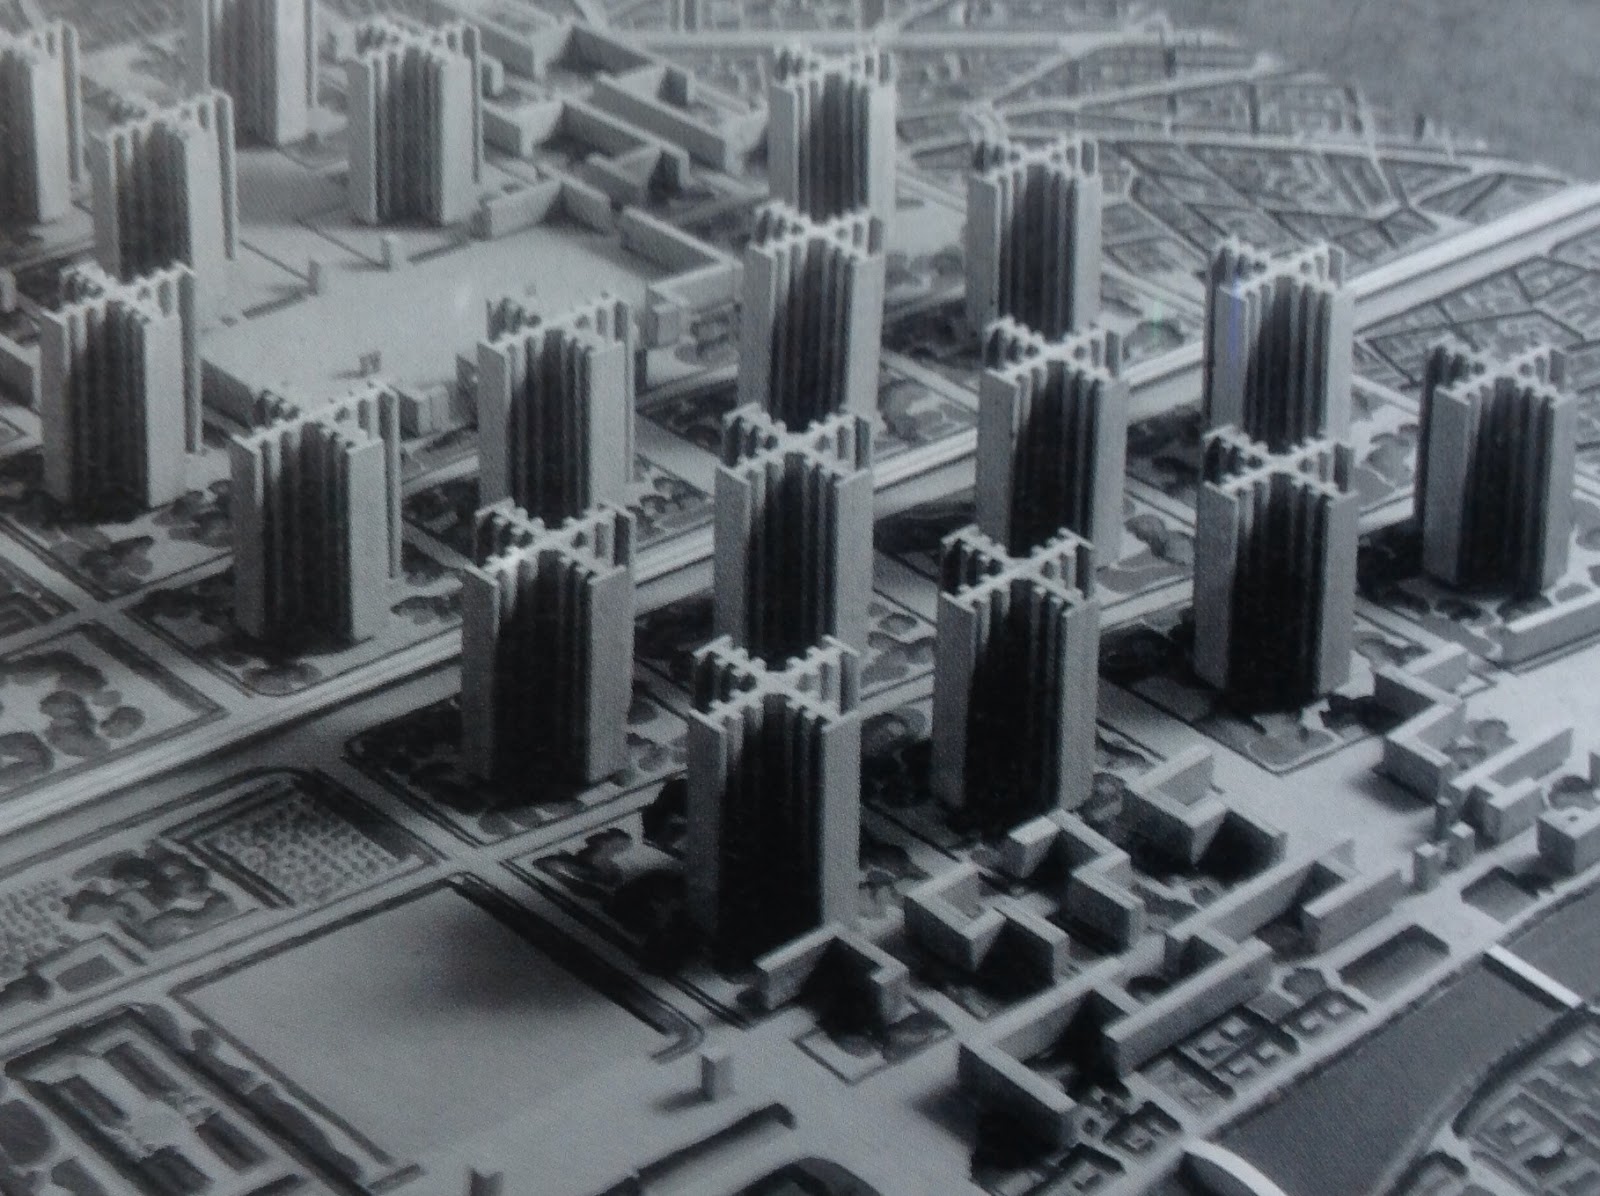
It is always difficult squaring the circle between objective and subjective approaches to project appraisal. I was reminded of the solution adopted for the schools' funding formula: central government sets the boundaries within which each local authority must work. On the one hand, there is an objective framework that is the equivalent of UCL's social value optimisation. On the other hand, local authorities tweak the formula to meet local needs. However, the option to consider non-financial measures barely features in the infrastructure regulation. Chris Green (SQW) and Nicholas Miles bemoaned that the majority of transport projects look only at 'time saved', which an optimiser would rapidly transform into something akin to Le Corbusier's Plan Voisin:


Several conference participants came up with alternative factors that local communities might want to consider: health, productivity, distributional effects, ecological value, direct consumption value, and so on. Goodhart's Law is clearly at play here: 'when a measure (journey time saved) becomes a target, it ceases to be a good measure'.

In several breakout sessions, we discussed how we might persuade private investors to look beyond short-term financial gain. Steve Keen berated economists for narrow-thinking, as did Sir Vince who plugged the 'brilliant book written by Manchester students'. But there was also room for optimism. Sir Vince highlighted the alternative business model of The People's Trust whose objective is to 'achieve sustainable, long-term growth' via an alternative investment fund 'owned 100% by our members'. This is not investment advice, but a £20 bet, to help them launch, seems worth it to ensure an alternative to non-interventionist pension funds.

To sum up: I took away two strategies if we are going to 'take back control'. First, put public funds to better use through localism, or social value index optimisation, or both. Second, reinvigorate private investor activism.

Wednesday, 27 April 2016

Pluralism since the ‘1992 Plea’ in the AER

First published on the Rethinking Economics Blog, March 12th 2014

In May 1992, a ‘Plea for a Pluralistic and Rigorous Economics’ was published in the American Economic Review (Vol 82 No. 2). It was signed by Harcourt, Galbraith, Goodwin, Kindelberger, Minsky, Pasinetti and other eminent economists. The Plea was funded by FEED who launched a second ‘Plea’ in 2009 and support the 2012 ‘Manifesto for Economic Sense’.  Geoffrey Hodgson, Research Professor in Business Studies at the University of Hertfordshire and one of the co-organisers of the ‘1992 Plea’, is interviewed here about the history of economic pluralism, and the challenges facing economics today.


NL: Twenty two years after the ‘1992 Plea’, do you think the mainstream has changed?
GH: I think things have changed in economics, to some degree. It’s not entirely positive, but in some senses economics is more diverse now that it was twenty two years ago… for example, new areas like experimental economics and behavioural economics have gained respectability. The main problem now with economics is not so much its diversity, or its insufficient internal pluralism, but the way that technique dominates and gets in the way of substance. Economists are engaged with mathematical puzzle solving rather than real-world problems…
NL: By that you mean things like regression analysis and theoretical model building?
GH: Theoretical model building and econometrics … that is all that now seems to matter in terms of publication in top journals or academic promotion. The whole discipline has become dominated by people who are very clever in technique but innocent of many important aspects of the real world and the history of their own discipline.
NL: In that 1992 Edition of the AER there were some pluralist surveys of economists, do you think the AER would publish that kind of qualitative research today?
GH: Generally it is very difficult to publish anything like that, and not just in the AER. I include other leading journals, like the Quarterly Journal of Economics or the Economic Journal in the UK… although occasionally they publish qualitative pieces, to spice up interest in their journal.
NL: What successes have you seen in the campaign for pluralism?
GH: The ‘1992 Plea’ was an early ringing of alarm bells about the nature of the discipline and the way it had been developing. It may have stimulated further similar complaints, such as from the French student movement… and dispersed attempts in Cambridge and also in the US… but the real change came with the 2008 crash. This provoked a much larger tide of complaint among students and others about the alleged inadequacies of mainstream economics.
NL: Was there a pluralist movement prior to the ‘1992 Plea’?
GH: Several prominent economists had made complaints. The petition was preceded by an important 1988 report by a commission of the American Economics Association, called ‘Report by the Commission on Graduate Education’ (Krueger et al, 1991), which complained about the dominance of technique in the discipline. A number of leading individuals, including Milton Friedman, also complained about the subject turning into advanced mathematics.  The most important event was the 1988 commission and its critical and scathing report.
NL: Did it have any success at the time?
GH: No.
NL: So why do you think the profession keeps coming back to these very inward-looking methods?
GH: The economics profession has an internal reward system that gets reinforced and replicated. Someone once compared it to the peacock’s tail. Once this positive feedback loop gets established, then people look for the glorious tail feathers despite their questionable usefulness. Fancy mathematics gets economists published and gets them promoted. As those people rise in the profession they will recruit people who perform similarly and the same kind of behaviour gets replicated. Other people, who think more widely or philosophically, or are more interested in the history of the subject or how it has changed, or who look more deeply at the conceptual assumptions, don’t get considered for influential positions in the discipline.
NL: What advice would you give Rethinking Economics?
GH: I hate to be pessimistic, because I don’t want to dampen the enthusiasm of those people committed to this, but unless you get some of the top universities appointing professors who are more broad-minded, who are not dominated by technique, who have influence, and some of the top journals consider more conceptual, historical material rather than simply technique-driven material,  then it will fail. Mark Blaug, who was a friend of mine who died a couple of years ago, got very pessimistic about this, and so did Ronald Coase who died last year. Another problem is that American economics is now overwhelmingly dominant. I often ask people… can you name a living British economist…  and they really have difficulty thinking of anybody. When mainstream economists took over the Cambridge department in the 1980s, after the era of Robinson and Kaldor, their explicit aim was to make Cambridge a rival to the top American Universities In other words, they aimed not to develop Cambridge’s own niche, but simply to follow what America was doing. You are inevitably 5 years behind if you are lucky, and that US emulation has led to the near-destruction of British economics… with this subservient mentality it is very difficult to change things in the UK.
NL: Can we talk about your hope for the future?
You may have heard of a new association called WINIR: the World Interdisciplinary Network for Institutional Research. What we are trying to do is create a new field for study. It’s not just about economics, but institutional economics is a part. I think that this is a more productive strategy than trying to change economics…  but the problem with WINIR is it doesn’t cover everything. At the moment, it omits crucial areas like finance… we can’t do everything. We are hoping to find new ways of promoting realist approaches and developing new ideas
NL: When you look at Blanchard’s work at the IMF…  is there at least a sense that more reflective research is coming out, even on the finance side?
GH: That’s right, and there are other good examples, like Thomas Piketty’s work on capital and inequality…. but these are the exceptions. All the incentives, all the ways that you get promoted in the system are not by thinking outside of the box. When I gave a talk to the Post-Crash group in Manchester, I said you have to take the institutions of science seriously. One of the problems with heterodox criticism is that it’s a fragmented growth of people who can’t agree amongst themselves on much, except that they are opposed to the mainstream: that will never generate cumulative knowledge. We actually need an alternative centre of orthodoxy. Science cannot progress by questioning everything, all the time….  some assumptions or knowledge has to be taken for granted. These assumptions may need to be changed later, but we need consensus as much as pluralism. Hence I’m against organising opposition to mainstream economics on the basis of a ‘heterodox’ label…  in fact there are many good and interesting things going on in the mainstream.  Heterodox organisations and leading figures who work under that label often overlook potential allies in the mainstream…
NL: One of the things we are struggling with in the UK curriculum review is the word ‘CORE’… this Popperian idea of a heuristic around which everything else revolves…  is the idea of a ‘CORE’ something the profession can escape?
GH: I think the CORE idea is important: the problem with things at the moment is that the core is defined in terms of technical skills. An undergraduate doing an economics degree has to understand key aspects of game theory, to understand key certain econometric techniques, and these take up the time of teaching and testing for the student… and as the bar is always being lifted… because the complexities of game theory and econometrics are always increasing…  so it’s not so much changing the subject matter of the core, it’s changing the preoccupation of the core. We need to establish that the first and foremost job of an economist is to understand the economy…  all other things are subservient to that.
Many heterodox economists blame Marshall, among others, for what went wrong. He was part of the neoclassical revolution of the 1870s and 1880s. But if you actually look at how Marshall wrote and how he behaved he was extremely tolerant and open minded…  he wrote in his Principles and also in his letters that economic theory is not a mathematical toy. He argued that we have to understand the real world. For him, mathematics was a tool, but not the main part of the subject…
NL: Several of the petitions for pluralism talk about solving climate change, global warming, inequality, wealth accumulation, capital flight, all of these issues. Do you agree that economics is that broad? Can economics solve all of these problems or is that too grand a claim?
GH: Marshall’s definition of economics was the study mankind in the ordinary business of life: by that he meant processes concerning the generation of wealth and its distribution, which include problems like the impact of climate change…  we need to develop economic policies to deal with climate change in some way.
NL: Which includes solving these issues…
GH:  Yes.
NL: Could you recommend three pieces of your work to a student interested in pluralism?
GH:  My 2004 book on institutional economics; my 2013 book on evolutionary economics; and my book on capitalism that is coming out this year. Each book addresses the issue of pluralism and challenges mainstream assumptions.
NL: Thank you very much.

References
Hodgson, Geoffrey M. (2004) The Evolution of Institutional Economics: Agency, Structure and Darwinism in American Institutionalism (London and New York: Routledge).
Hodgson, Geoffrey M. (2013) From Pleasure Machines to Moral Communities: An Evolutionary Economics without Homo Economicus (Chicago: University of Chicago Press).
Hodgson, Geoffrey M. (forthcoming) Conceptualizing Capitalism: Institutions, Evolution, Future (Chicago: University of Chicago Press).
Krueger, A.O. Arrow, K.J. et al (1991). Report of the commission on graduate education in economics.  Journal of Economic Literature. 29(3):1035-1053
Various (1992). A Plea for a Pluralistic and Rigorous Economics”, American Economic Review, 82(2):25